Independent Financial Research & Analysis
Daily briefings, 7,700+ real-time charts, and macro insights from Dr. Ed Yardeni and his research team.
Research
Latest Research
Recent insights from our research team
On China’s Banking Crisis & New Trade Flexibility
In consolidating its banking system, William reports, China risks repeating the mistakes Japan made in the 1990s when bad loans simply migrated to new balance sheets instead of being recapitalized. That paved the way to years of deflation and near-zero interest rates. … Also: Uncharacteristically, China has agreed to EU demands to halve its hybrid vehicle shipments to Europe, deescalating tensions between the two and perhaps opening the door to similar deals for other industries. What does China’s new conciliatory tack imply for its trade negotiations with other economies? Does the deal represent a new model for global trade?
Sizing Up US Debt
I. Adding It Up The bond market had a good day today: It was closed for Columbus Day. We think that yields have risen high enough to attract buyers. If so, then yields should stabilize around current levels. Plenty could still go wrong, making bond yields even more attractive. The war in the Middle East is likely to heat up again after the midterm elections, sending oil prices higher. On the other hand, this week's core CPI is likely to rise just 0.2%, which would likely postpone a Fed rate hike from later this month to early December. For now, let's focus on the supply of debt in the US, which is a longer-term concern for the bond market. The US Treasury borrowed $749 billion during the three months through September (chart). That's the change in marketable securities held by the public over the three months. The 10-year Treasury bond yield rose from roughly 4.50% to 5.25% over that period. In the past, the supply of government securities rarely seemed to drive bond yields. The key drivers were expected and actual inflation and the Fed's reaction to both. In the past, federal budget deficits tended to widen the most during recessions, when tax revenues fell faster than the government’s outlays (chart). The supply of Treasury securities would be increased as the Fed lowered interest rates to revive economic growth. The deficits would narrow during economic expansions, as revenues rose faster than outlays. Over the past three years, the economy has been booming, but the government’s budget deficit remains very wide. It hasn't narrowed because outlays are growing faster than receipts. Allowing that to happen is fiscal recklessness. That’s because it requires increasing the supply of government debt during an economic boom, when private credit demands are surging, which necessarily puts upward pressure on interest rates. If rates get high enough to cause a credit crunch and a recession, attempts to revive the economy with deficit-bloating fiscal stimulus could backfire by pushing bond yields higher. If deficits are this large during good times, what happens when the bad times arrive? For now, we believe the backup in US bond yields is driven more by better-than-expected US economic growth than by the government's deficit. In our view, bond yields are back to their "old normal," i.e., consistent with robust economic growth. In other words, the US isn't on the edge of a debt crisis. In the Roaring 2020s scenario we expect, productivity-led economic growth boosts government revenues and lowers America's deficit and debt ratios relative to nominal GDP. Both Treasury Secretary Scott Bessent and Fed Chair Kevin Warsh believe this will happen. The question is whether the Bond Vigilantes will patiently wait for this outcome. We're not so sure. For perspective, let's add up US debt and compare it to public and private debt in other countries: (1) Total US debt reached a record $118.9 trillion in Q2, including $83.8 trillion in nonfinancial debt and $27.7 trillion in financial debt (chart). (2) The composition of nonfinancial debt has shifted dramatically since the Great Financial Crisis (GFC). Before 2008, Treasury debt was smaller than household and business debt. That relationship reversed as Washington borrowed heavily during the GFC while the private sector deleveraged. The Great Virus Crisis (GVC) in 2020 accelerated the shift. By Q2-2026, marketable Treasury debt held by the public had reached a record $30.9 trillion, exceeding both household and business debt (chart). (3) Relative to nominal GDP, total US debt has declined since the GVC to 374.1% in Q2 (chart). The financial sector drove much of the decline, with financial debt falling from around 150% to 87.0% of GDP since the GFC. Nonfinancial debt is at 263.8%, remaining relatively stable in recent years despite rising government debt, with a brief exception during the GVC. That stability masks a significant shift. Treasury debt has surged from around 30% of GDP before the GFC to 97.2% in Q2, while household debt has fallen from nearly 100% to 67.0% and business debt has also declined (chart). Private-sector deleveraging has partly offset rising government indebtedness relative to GDP. Separating Treasury debt from total nonfinancial debt makes the divergence even clearer. Nonfinancial debt excluding Treasuries has fallen from roughly 200% of GDP during the GFC to 166.5% in Q2, as Treasury debt surged to 97.2% of GDP (chart). (4) Total US debt securities and loans reached a record $120.1 trillion in Q2, comprising $67.3 trillion in securities and $52.7 trillion in loans (chart). Securities have grown faster than loans since the GFC. Marketable Treasury securities held by the public have surged to $30.9 trillion, far exceeding corporate and foreign bonds, which they overtook following the GFC (chart). Government borrowing has become increasingly dominant in US debt markets. In short, private-sector debt is down relative to GDP since the GFC, while the public sector has become more indebted relative to GDP. Healthier household and business balance sheets should make the economy more resilient to future shocks, reducing the potential need for government bailouts and additional borrowing. That could help preserve Treasuries' traditional role as a safe haven during the next crisis, despite elevated government debt. II. Global Comparisons (1) Total debt/GDP. Japan leads the pack, followed by France, Canada, and China. The US is roughly in line with the developed country average, while Germany has the lowest debt ratio among the countries shown (chart). (2) Government debt/GDP. Japan also tops the government debt ranking, followed by Italy and China. The US and France are well above the developed country average, while Germany stands out with a relatively low government debt burden (chart). (3) Private debt/GDP. Canada, France, and China have the highest private-sector debt ratios, while the US ranks below the developed country average. Italy has the lowest private-sector debt ratio among the countries shown (chart).
When American Consumers Are Depressed, They Go Shopping!
Consumer spending may seem to be defying economic gravity—remaining robust in the face of depressed consumer confidence, affordability concerns, and elevated interest rates. Indeed, the saving rate is dropping toward zero and could even turn negative by the end of the decade. Today, Ed and Elias explain why that’s no worry; why consumer spending has been so resilient, like the economy itself this decade; and why they expect the resilience of both to continue. … Also: Inflationary expectations are on the rise. That raises the risk that so are secondary inflationary effects from this year’s inflationary shocks. And that raises the probability that the Fed’s September rate hike won’t be the last this year. … And: Dr Ed reviews “Lioness” (+).
Archive
Our Research Library
19 years of daily research, charts, and analysis
Topics
QuickTakes Topics
Timely commentary covering the most important market themes
Charts
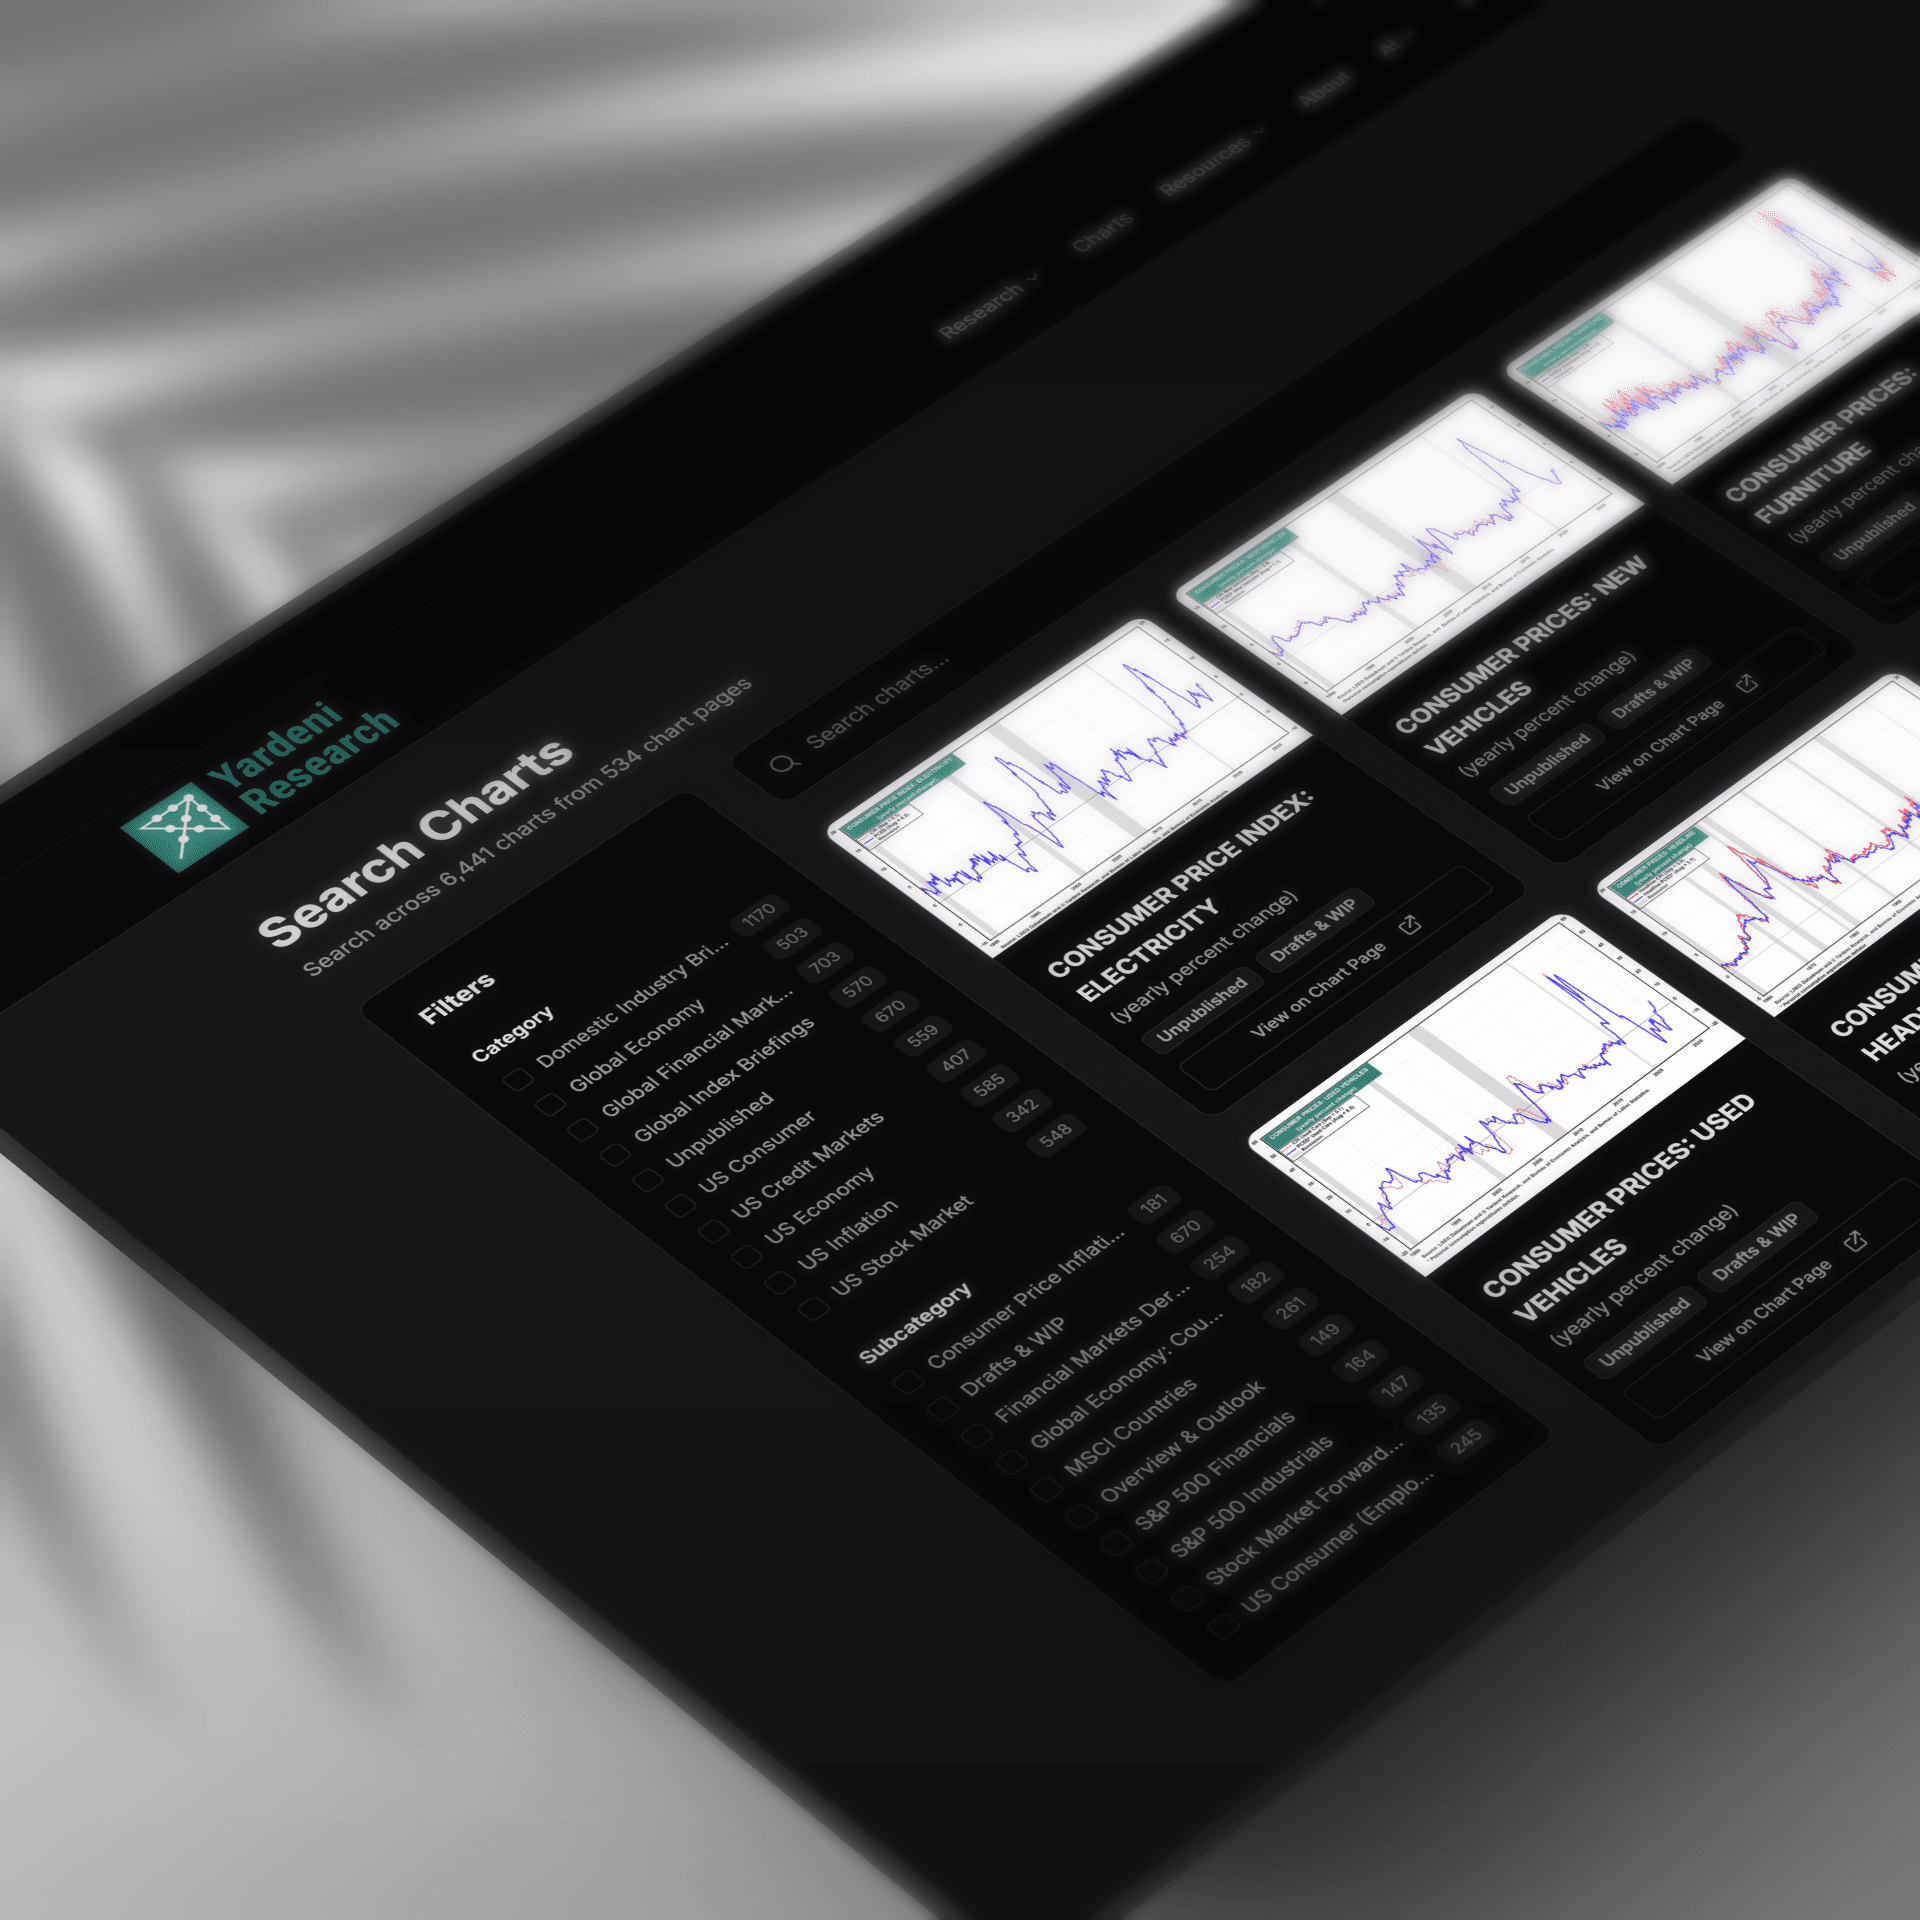
Find Any Chart in Seconds
Search across 7,740+ real-time charts with instant visual previews
GENERAL MOTORS: STOCK PRICE (GM)
S&P 500 TRANSACTION & PAYMENT PROCESSING SERVICES: INDEX, FORWARD EARNINGS & VALUATION
S&P 500 TRANSACTION & PAYMENT PROCESSING SERVICES: FORWARD REVENUES PER SHARE
S&P 500 TRANSACTION & PAYMENT PROCESSING SERVICES: FORWARD PROFIT MARGIN
Sample charts from our collection of 7,740+ visualizations
Tools
Research Tools
Interactive dashboards for tracking economic conditions and market trends
Beige Book Monitor
Fed economic conditions across 12 districts with traffic-light signals.
FOMC Policy Meter
Dovish-to-hawkish policy stance tracker across FOMC meetings.
FOMC Minutes Monitor
Hawk/dove signal extraction across 10 economic themes.
FOMC SEP Monitor
Fed projections and dot plot distributions across meetings.
FOMC Statements
Every FOMC policy statement since 1997 — full text, rates, and voting records.
Private Credit Monitor
Auto-updating chronology of the private credit liquidity crisis.
Release Calendar
Major publications from the Fed, ECB, IMF, and 12 global institutions.
Try Yardeni Research free for four weeks.
Full access to everything we publish. No credit card, no obligation.